Self-Employed Tax Guide
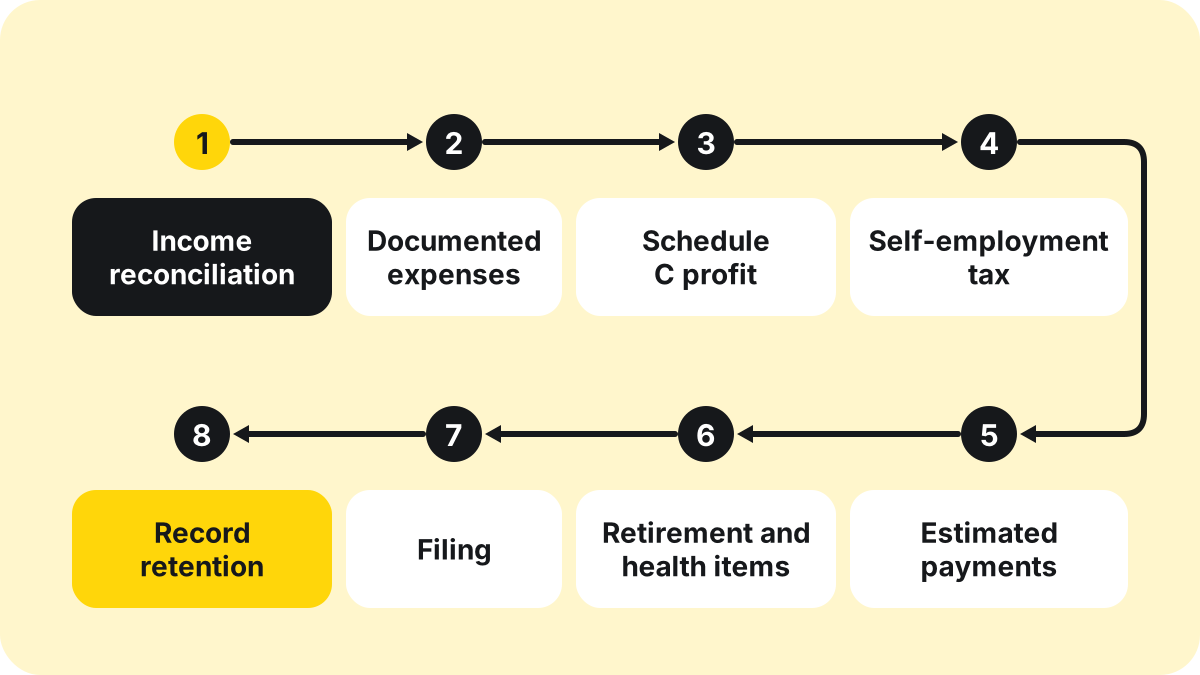
Self-employed taxpayers generally must track all business income, document ordinary and necessary expenses, calculate income and self-employment taxes, and pay through withholding or estimated payments during the year.
Short answer
Self-employed tax compliance begins with accurate books. Report all income, classify documented business costs, allocate mixed use, distinguish assets from expenses, calculate income and self-employment taxes, and update estimated payments using the complete household picture. Add professional advice when entity, payroll, state, foreign, or disputed-classification issues exceed a simple Schedule C.
At a glance
7min read
Confirm what activity and entity are being taxed
Build books before building the return
Reconcile all business income
Classify ordinary and necessary business expenses
Allocate mixed-use expenses
Key takeaways
- 1
Report all business income from books and records, including amounts received without a Form 1099.
- 2
Separate business and personal activity and retain evidence of amount, date, vendor, purpose, and allocation.
- 3
Schedule C profit can affect both federal income tax and self-employment tax; plan cash throughout the year.
- 4
Estimated-tax requirements depend on the complete household return and timing, not a fixed percentage of each deposit.
- 5
Entity choice, worker classification, payroll, sales tax, state filing, retirement, and health deductions require their own analysis.
Read the guide
A 1099 threshold does not determine whether income is taxable, and a business bank withdrawal does not determine whether an expense is deductible. This guide builds a practical federal workflow for sole proprietors and gig workers while flagging entity, payroll, state, and international issues that need separate advice.
Confirm what activity and entity are being taxed
Self-employment generally includes carrying on a trade or business as a sole proprietor or independent contractor, including qualifying part-time and gig work. A single-member LLC is a state-law entity and is commonly disregarded for federal income tax unless it elects another classification; the LLC label alone does not create an S corporation.
Keep reading
Worker classification depends on control and the relationship, not a contract label or the worker’s preference. If an employer-employee relationship exists, compensation generally belongs on payroll rather than Schedule C. Misclassification can affect income tax, employment tax, benefits, and state obligations.
Build books before building the return
Use a separate business bank account and card where practical. Separation does not decide deductibility, but it makes reconciliation and evidence stronger. Choose a bookkeeping system that records:
- invoice or transaction date;
- customer and amount billed;
- amount, date, and method received;
- refunds and chargebacks;
- sales tax collected;
- platform or processing fees;
- vendor, expense, and business purpose;
- asset purchases and placed-in-service date;
- owner contributions and withdrawals;
- mileage and other contemporaneous logs.
Reconcile bank, card, payment-platform, cash, and marketplace accounts monthly. IRS recordkeeping guidance permits a system suited to the business if it clearly shows income and expenses and supports return entries.
Reconcile all business income
The IRS gig-work page says income must be reported even when the business does not receive a Form 1099. Information-return thresholds govern payer reporting, not whether the recipient’s receipts are taxable.
Create a gross-receipts reconciliation:
- Start with invoices, sales records, and platform reports.
- Add cash, checks, transfers, tips, barter, and direct payments.
- Reconcile Forms 1099-NEC, 1099-K, 1099-MISC, and other forms.
- Separate refunds, chargebacks, sales tax, and platform fees using consistent books.
- Explain differences between deposits and revenue, such as loans, transfers, owner capital, or payment timing.
Keep reading
Do not report only net platform deposits when the form and business books require gross receipts with fees deducted separately. Avoid counting the same transaction once from an invoice and again from a Form 1099.
If an information return is incorrect, request correction and document it. The return still needs an accurate, supportable position.
Classify ordinary and necessary business expenses
Publication 334 and the Schedule C instructions organize common sole-proprietor items. An expense generally needs a bona fide business purpose, documentation, and proper classification.
| Expense area | Evidence and question |
|---|---|
| Advertising | Vendor, campaign, business promoted, payment |
| Supplies | Item, use, inventory or current expense treatment |
| Software | Subscription period, business users, capitalization question |
| Professional fees | Service, business connection, invoice |
| Insurance | Policy, coverage period, business risk |
| Contract labor | Agreement, payment, worker classification, information reporting |
| Travel | Business purpose, itinerary, lodging, transport, personal days |
| Meals | Business relationship or travel context, attendees, limits |
| Vehicle | Mileage or actual-cost method, business-use log, ownership |
| Home office | Exclusive and regular business use, measurements, selected method |
Personal spending does not become deductible because it is paid from a business account. Clothing suitable for everyday wear, commuting, personal meals, and mixed vacations are common problem areas.
Allocate mixed-use expenses
Phone, internet, vehicle, home, equipment, and travel can serve both business and personal purposes. Choose a reasonable, documented allocation based on actual use and the applicable rule.
Keep reading
For vehicle use, maintain a contemporaneous mileage log with date, destination, business purpose, and miles. The standard mileage and actual-expense methods have different rules and elections. Commuting from home to a regular work location is generally personal, while travel between business locations may differ.
Home-office rules generally require regular and exclusive use, with exceptions for certain storage and daycare situations. A kitchen table used by the family is not exclusive. The simplified and actual methods calculate differently and can affect depreciation and later sale issues.
Separate expenses from assets and inventory
A cost that benefits multiple years may need capitalization and depreciation rather than an immediate deduction. Record description, cost, acquisition date, placed-in-service date, business-use percentage, method, and disposition.
Keep reading
Inventory and cost of goods sold require tracking beginning inventory, purchases or production, and ending inventory under applicable methods. Equipment purchased is not the same as supplies consumed. Elections such as Section 179 or bonus depreciation have tax-year rules, limits, business-use conditions, and state differences.
Startup and organizational costs incurred before an active business begins can follow special rules. Preserve them separately even if no revenue exists yet.
Understand Schedule C and Schedule SE
Many sole proprietors report business income and expenses on Schedule C attached to Form 1040. Net profit or loss then flows into other parts of the individual return. Schedule SE calculates self-employment tax under current rules.
Keep reading
Self-employment tax generally covers Social Security and Medicare components. The deductible portion of self-employment tax is an income-tax adjustment; it does not erase the self-employment tax itself. Additional Medicare tax and wage interactions can apply based on the household.
The IRS says a filing requirement can apply when net earnings from self-employment reach the statutory threshold, even for side, part-time, or temporary gig work. Other income or return requirements can require filing below that amount. Use the current Schedule SE and Form 1040 instructions.
Plan estimated taxes from the household return
Estimated tax can cover income tax, self-employment tax, and certain other taxes. The IRS estimated-tax page says sole proprietors, partners, and S corporation shareholders generally may need estimated payments when they expect to owe the applicable amount at filing.
Do not simply send a fixed percent of revenue without calculating profit and the rest of the return. Build a quarterly forecast with:
- year-to-date revenue and deductible expenses;
- expected full-year profit;
- spouse wages and household income;
- federal and state withholding;
- credits and adjustments;
- prior-year tax and safe-harbor requirements;
- self-employment and other taxes;
- payments already made.
Keep reading
Income can be annualized when it is uneven, subject to the form rules. A taxpayer with wages may increase Form W-4 withholding instead of or alongside estimates. Withholding timing can receive different treatment from estimated payments.
Save payment confirmation and verify it posts to the correct taxpayer, form, and year. Federal, state, local, franchise, and sales-tax payments are separate systems.
Review health insurance and retirement options
Eligible self-employed health insurance can create an adjustment to income, subject to net-profit, employer-plan, and other rules. Health savings account eligibility and contributions are separate.
Keep reading
Self-employed retirement options can include SEP, SIMPLE, and one-participant 401(k) plans. Contribution limits, compensation definitions, establishment dates, employee coverage, filings, and deadlines differ. Choosing a plan after year-end from a generic calculator can produce an unavailable contribution.
Coordinate retirement contributions with estimated cash needs and the final business profit. Entity owners and common-law employees can change the calculation significantly.
Do not treat an S corporation as a shortcut
An S corporation election changes payroll, return filing, compensation, distributions, basis, and administrative requirements. It does not automatically eliminate all Social Security or Medicare tax. Shareholder-employees performing services generally need reasonable compensation under applicable rules.
Compare potential tax effects with payroll service, separate return, bookkeeping, state fees, unemployment, retirement-plan, insurance, and compliance costs. Make an entity election with professional advice before assuming an online estimate applies.
Address other business obligations
Depending on facts, self-employed taxpayers may need:
- an Employer Identification Number;
- payroll and employment-tax filings;
- contractor information reporting;
- sales and use tax registration;
- state income, franchise, or gross-receipts returns;
- city or county licenses;
- beneficial ownership or industry reporting under current law;
- foreign account or international information returns.
Income-tax software does not automatically handle every obligation. Build a compliance calendar by jurisdiction and business activity.
Review and retain the final file
Before filing, reconcile Schedule C gross receipts to the books, Forms 1099, and deposits. Tie every expense category to the ledger and inspect negative or unusually large amounts. Confirm vehicle, home-office, meal, asset, inventory, and contractor treatment.
Keep reading
Save the return, Schedule C, Schedule SE, worksheets, depreciation schedules, payment history, books, bank reconciliations, receipts, contracts, logs, and filed information returns. IRS guidance says records must be kept as long as needed to prove income or deductions; asset basis and employment-tax records can require longer retention.
Update the bookkeeping system after filing so tax adjustments and carryovers are reflected in the next year.
Glossary
Frequently asked questions
Do I report self-employment income if I did not receive a 1099?
Yes. IRS guidance says business and gig income must be reported even when no information return is issued. Reconcile gross receipts from books and payment records.
Can I deduct every purchase made from my business bank account?
No. The expense must satisfy the applicable business and substantiation rules. Personal spending remains personal, and assets, inventory, reimbursements, and mixed use require separate treatment.
More answers (3)
How much should I set aside for taxes?
Calculate from expected net profit and the complete household return, including self-employment tax, income tax, state tax, credits, withholding, and safe-harbor rules. One percentage does not fit every taxpayer.
Does an LLC reduce self-employment tax?
An LLC is a state-law entity and its default federal tax classification depends on ownership. It does not by itself reduce tax. Elections such as S corporation status add payroll, compensation, return, basis, and state issues.
How long should I keep self-employed records?
Keep records as long as needed to substantiate income, deductions, assets, and returns. Employment tax, basis, depreciation, carryover, and property records can require longer retention.
Try the numbers yourself
Sources (5)
Facts checked Updated- IRS — Small Businesses and Self-Employedirs.gov
- IRS — Manage Taxes for Gig Workirs.gov
- IRS — Estimated Taxesirs.gov
- IRS — Recordkeepingirs.gov
- IRS — Publication 334: Tax Guide for Small Businessirs.gov
Fact-check dates show when the published facts were checked against the cited sources. They do not guarantee that terms have stayed the same.